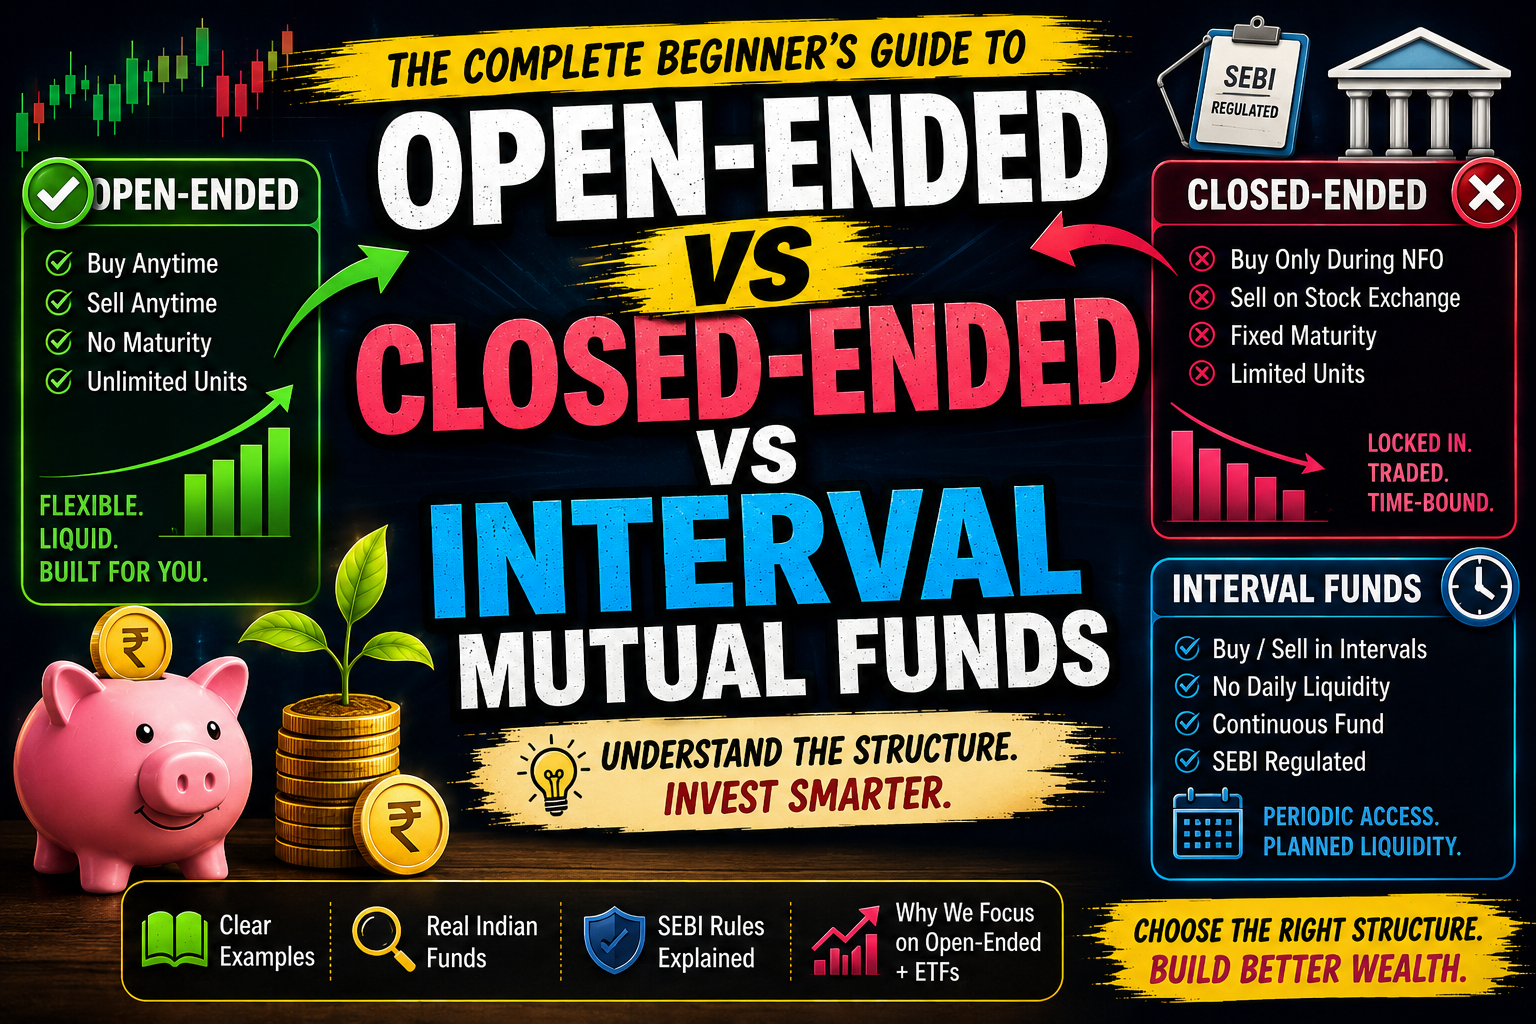
Open-Ended vs Closed-Ended vs Interval Mutual Funds: The Complete Beginner's Guide to Fund Structure
Note
Who this is for: Anyone who has scrolled past a fund with "Series III" or "Interval Plan" tacked onto its name and wondered what that meant — or anyone who has simply never questioned why every fund they own lets them buy and sell whenever they want. By the end of this guide, you'll know exactly how mutual funds are structured in India, why one structure quietly dominates the entire industry, and why this website's analysis is built entirely around it.
1. A Question Most Investors Never Ask
Ask a hundred mutual fund investors in India what "open-ended" means, and most will shrug. Not because it's a hard concept — because they've never needed to know it. Every fund they've ever bought, every SIP they've ever set up, has quietly belonged to the same structural family, so the label never mattered.
But open a fund screener and filter by "scheme type," and a different world appears. Names like SBI Tax Advantage Fund — Series III, ICICI Prudential Growth Fund — Series 2, and UTI Fixed Income Interval Fund — Annual Plan show up alongside the familiar HDFC Flexi Caps and Parag Parikh Flexi Caps of the world. These aren't typos or oddly named siblings of the funds you know. They belong to entirely different structural categories — closed-ended and interval funds — that operate under a completely different set of rules for when you can put money in and when you can take it out.
This blog explains all three structures — open-ended, closed-ended, and interval — from first principles, with worked examples and real Indian funds. And by the end, we'll use everything you've learned to answer a question this website gets asked often: why do we only ever analyse open-ended funds and ETFs, and never touch a closed-ended or interval scheme?
2. Before We Begin: What "Structure" Actually Means
Every mutual fund classification you've heard of — large-cap, flexi-cap, debt, hybrid — describes what the fund invests in. Structure is a different, more fundamental axis entirely. It describes when you're allowed to enter and exit the fund, and that single design choice ripples into almost everything else about how the fund behaves.
Two funds can hold an almost identical portfolio of stocks or bonds, yet behave completely differently as investments, purely because of their structure. One might let you invest ₹500 a month via SIP and exit within three working days whenever you like. The other might take your money once, lock it up for five years, and give you no direct way back to the fund house at all before then.
SEBI (the Securities and Exchange Board of India) recognises exactly three structural categories for mutual fund schemes in India:
1. Open-ended schemes 2. Closed-ended schemes 3. Interval schemes
Let's take each apart in detail.
3. Open-Ended Funds: The Structure Behind Almost Everything You Own
An open-ended fund has no fixed maturity date and no cap on how many units it can issue. It stays open for investment and redemption on every business day, indefinitely, until the day it's eventually wound up by the AMC (which is rare and unrelated to structure).
How It Actually Works
When you invest ₹10,000 in an open-ended fund, the AMC doesn't buy your units from some existing pool of sellers — it creates brand new units for you at that day's Net Asset Value (NAV) and adds your money to the fund's pool of assets. When you redeem, the reverse happens: the AMC cancels your units and pays you out of the fund's assets. There's no buyer needed on the other side of your trade, because the fund itself is always the counterparty.
This is precisely why open-ended funds can absorb unlimited flows of money. If a million new investors decide to start a SIP in the same fund tomorrow, the fund simply creates a million sets of new units. There's no ceiling.
The Trade-Off Nobody Talks About
This flexibility isn't free for the fund manager. Because investors can ask for their money back on any business day, the fund must always keep a portion of its assets in cash or highly liquid instruments to honour redemptions — typically a small buffer, even in equity schemes. During a market panic, when everyone tries to exit at once, the fund manager may be forced to sell portfolio holdings at exactly the wrong moment, purely to raise cash for redemptions. This is the quiet cost of the flexibility you take for granted.
A Worked Example: How Units Get Created
Suppose an open-ended flexi-cap fund has an NAV of ₹85 on a given day. You invest ₹8,500. The AMC allots you exactly 100 new units, and the fund's total assets under management rise by ₹8,500. If, the same day, another investor redeems 50 units at the same NAV, the AMC pays them ₹4,250 and those 50 units simply cease to exist. The fund's unit count and asset base expand and contract every single day based on nothing but investor behaviour — not because of any external market for the units themselves.
Why This Is the Default Structure in India
Virtually every fund category you recognise by name — large-cap, mid-cap, small-cap, flexi-cap, ELSS, liquid, corporate bond, balanced advantage, arbitrage — is, in practice, offered in open-ended form. According to AMFI's own industry data, open-ended schemes across equity, debt, hybrid, and passive categories together represent well over 99% of the entire Indian mutual fund industry's assets. Closed-ended and interval schemes combined are a rounding error by comparison — a fact we'll return to with hard numbers later in this guide.
Tip
A simple mental shortcut: if a fund's name doesn't contain the words "Series," "FMP," "Fixed Maturity," or "Interval," and it isn't an ELSS you bought before 2018, it's almost certainly open-ended. Every fund you've likely invested in through Groww, Zerodha Coin, Kuvera, or an AMC's own Direct plan portal falls into this category.
4. Closed-Ended Funds: The Fixed-Term Commitment
A closed-ended fund flips the open-ended model on its head. It accepts money only during a limited New Fund Offer (NFO) window — SEBI rules cap this subscription period at 30 days — and once that window shuts, the fund never issues a fresh unit again. There's a predetermined maturity date, typically somewhere between 3 and 7 years out, and until that date arrives, you cannot ask the AMC to redeem your units.
The Twist: You're Not Completely Locked Out
Here's what surprises most first-time readers: SEBI mandates that every closed-ended scheme must be listed on a recognised stock exchange (NSE or BSE) shortly after the NFO closes. So while you can't go to the AMC and redeem before maturity, you can, in theory, sell your units to another investor on the exchange — exactly like selling a stock.
The catch is that the price you get on the exchange is not the fund's NAV. It's whatever price a buyer is willing to pay right then, which depends entirely on the demand and supply for that specific fund's units on that specific day. Because most closed-ended funds trade in tiny volumes — often just a handful of trades in a week, or none at all — this "listing" is a legal safety valve more than a genuinely usable exit route for most retail investors.
The Premium/Discount Mechanic: A Worked Case Study
This is the single most important mechanical concept to understand about closed-ended funds, so let's walk through it with real numbers.
Suppose a closed-ended equity fund has a published NAV of ₹52 per unit — this is the true, audited value of one unit's share of the fund's underlying stock portfolio. Now suppose you need to exit two years before maturity and place a sell order on the exchange.
Scenario A — the fund trades at a discount: Because trading volumes are thin and few buyers are actively watching this fund, your sell order only finds a buyer at ₹46 per unit — an 11.5% discount to NAV. If you hold 5,000 units, you receive ₹2,30,000 instead of the ₹2,60,000 your units are actually worth on paper. That ₹30,000 gap is not a fee, a tax, or an exit load — it's pure illiquidity cost, vanishing simply because there weren't enough buyers at the fair price on the day you needed to sell.
Scenario B — the fund trades at a premium: Occasionally, a closed-ended fund with a strong recent track record sees enough buying interest that its units trade at ₹58 — an 11.5% premium to NAV. In this case, a seller benefits and a buyer overpays. Some sophisticated investors deliberately hunt for closed-ended funds trading at steep discounts, betting that the gap will narrow — effectively trying to buy ₹1 of underlying assets for 85–90 paise. This is a legitimate strategy, but it requires active monitoring of exchange prices and is far removed from the "invest and forget" experience most retail SIP investors expect.
Warning
The listing isn't real liquidity for most people. A stock exchange listing satisfies SEBI's regulatory requirement, but if only a few hundred units change hands in an entire month, you cannot assume you'll find a fair-price buyer the day you need cash. Treat a closed-ended fund's tenure as if it were fully locked, and treat any exchange-trading exit as a bonus you might not get to use.
Why Fund Managers Actually Like This Structure
The absence of redemption pressure is a genuine advantage from the fund manager's chair. Knowing the exact size of the corpus for the entire tenure lets a manager take positions in stocks that may need years to play out, without worrying that a market downturn will force forced selling to meet redemptions. This is precisely why closed-ended debt funds like Fixed Maturity Plans (FMPs) became popular: the fund can buy bonds that mature almost exactly when the scheme itself matures, locking in a yield with minimal interest-rate risk along the way — something an open-ended debt fund, which must always stay liquid, cannot replicate as cleanly.
Real Closed-Ended Funds in India
Genuine, currently recognisable examples include SBI Tax Advantage Fund – Series III, ICICI Prudential Growth Fund – Series 2, and various Fixed Maturity Plans launched by AMCs like HDFC and the erstwhile Reliance (now Nippon India) Mutual Fund. Most of these ELSS "Series" funds were launched before 2018 — a detail with an important regulatory story behind it, which we'll get to in Section 13.
Analogy: The One-Way Train
Think of a closed-ended fund as boarding a direct train with no intermediate stops. Once you're on board and the doors close, you're committed to riding all the way to the terminus — the fund's maturity date. There is technically an emergency cord you can pull mid-journey (the exchange listing), but pulling it means jumping off a moving train: possible, but costly, undignified, and not something to plan your journey around.
5. Interval Funds: The Middle Path Almost Nobody Takes
Interval funds sit deliberately between the other two structures. Like open-ended funds, they generally allow you to invest at any time. But like closed-ended funds, they only let you redeem during specific, pre-announced windows — called transaction periods — typically occurring monthly, quarterly, half-yearly, or annually, as specified in the scheme's offer document.
The Regulatory Mechanics
SEBI requires every transaction window to stay open for a minimum of two days, with at least a 15-day gap between the end of one window and the start of the next. Outside these windows, your money is simply inaccessible from the fund house — full stop. Like closed-ended funds, interval fund units must also be listed on a stock exchange to provide a theoretical (if usually thin) exit route between windows.
Miss your window, and in most schemes your units simply roll over — you wait for the next one. There's no penalty beyond the inconvenience, but there's also no shortcut.
What Makes Interval Funds Different From a Closed-Ended Fund
A closed-ended fund has a single maturity date and then ceases to exist. An interval fund typically has no final maturity — it just keeps rolling forward, opening its transaction window again and again, indefinitely. This makes it closer in spirit to a "perpetual" fund with scheduled, gated liquidity rather than a fund with a hard expiry.
An Important Local Nuance
If you search generally about interval funds, you may find descriptions of them investing in private equity, real estate, or hedge-fund-style alternative assets — this is common in some other markets. In India, that description doesn't match reality. The vast majority of Indian interval funds are conservative, debt-oriented schemes investing in government securities, high-quality corporate bonds, and money market instruments. Their purpose isn't exotic alternative-asset access — it's giving a debt fund manager the freedom to hold slightly less liquid, marginally higher-yielding bonds without worrying about daily redemption pressure.
Real Interval Funds in India
Genuine examples include UTI Fixed Income Interval Fund (Annual and Quarterly plans), Nippon India Interval Fund – Quarterly Series, IDFC (now Bandhan) Yearly Series Interval Fund, Aditya Birla Sun Life Interval Income Fund, and various ICICI Prudential and SBI interval plans launched as periodic series. Historical annualised returns for these debt-oriented schemes have typically clustered around 6% to 8.5% — modestly above what a comparable liquid or ultra-short-duration fund might offer, in exchange for the liquidity you give up.
A Worked Example: The Cost of Missing a Window
Suppose you invest ₹5 lakh in an annual interval fund in April, with the sole redemption window falling every March. In September, an unexpected expense arises and you need ₹2 lakh. You cannot redeem from the AMC — the next window is six months away. Your only options are to wait, or to attempt a sale on the stock exchange, where — just as with closed-ended funds — thin trading volumes may mean no buyer shows up at a fair price, or none at all.
Important
The critical tax change since April 2023: Under Section 50AA of the Income Tax Act, mutual fund schemes that invest 35% or less of their assets in domestic equity — which describes nearly every Indian interval fund — are classified as "Specified Mutual Funds." Gains from units of these funds bought on or after 1 April 2023 are taxed entirely at your income slab rate, regardless of how long you hold them. The old benefit of lower long-term capital gains tax with indexation no longer applies to fresh purchases in this category. This single change significantly reduced the tax-efficiency edge that interval and closed-ended debt funds used to hold over fixed deposits.
Analogy: The Cooperative Society Withdrawal Counter
Picture a housing society that lets you deposit money into a common maintenance fund any day of the year, but only opens its withdrawal counter for one week every quarter. You can plan around it if you know your needs in advance. But if an emergency falls in the eleven weeks the counter is shut, no amount of urgency changes the calendar.
6. Side-by-Side: How the Three Structures Actually Compare
| Feature | Open-Ended | Closed-Ended | Interval |
|---|---|---|---|
| Entry | Any business day | Only during NFO (max 30 days) | Any business day |
| Exit from the AMC | Any business day, at NAV | Not until maturity (3–7 years typically) | Only during transaction windows, at NAV |
| Exchange listing | Only ETFs trade on exchange | Mandatory | Mandatory |
| Transaction price outside AMC route | N/A (redeem at NAV directly) | Market price — can be at premium or discount to NAV | Market price between windows; NAV during windows |
| Maturity | None (perpetual) | Fixed (3–7 years typical) | None (perpetual, but gated) |
| SIP available | Yes | No — lumpsum only, during NFO | Rarely, and limited |
| Historical track record at purchase | Full multi-year history available | None — it's a brand-new scheme | Depends on the specific series' age |
| Redemption pressure on fund manager | High — must hold a liquidity buffer | None until maturity | Low, and predictable |
| Typical underlying assets | Everything — equity, debt, hybrid, index | Equity (locked strategies), FMPs (debt) | Overwhelmingly debt in India |
| Share of Indian MF industry AUM | Well over 99% | Under 0.5% combined with interval | Under 0.5% combined with closed-ended |
7. Liquidity in Practice: What Happens When You Actually Need the Money
Numbers on a comparison table are one thing; a real emergency is another. Consider three friends, each investing ₹5 lakh in 2021, each hit by an unplanned need for cash in 2023.
Ananya put her ₹5 lakh into an open-ended flexi-cap fund. When a medical emergency arrives in 2023, she logs into her app, places a redemption request, and has the money in her bank account within three working days. The fund's NAV that day is what she gets — no discount, no waiting, no exchange required.
Vikram put his ₹5 lakh into a closed-ended equity fund NFO with a five-year tenure maturing in 2026. Facing the same emergency, he discovers the AMC cannot redeem his units for another three years. His only route is the stock exchange, where his fund — trading in modest volumes — only finds a buyer at a 12% discount to NAV. He effectively loses ₹60,000 of value purely because he needed the money at the wrong moment in the fund's fixed lifecycle.
Meera put her ₹5 lakh into an annual interval debt fund, with the sole redemption window falling every March. Her emergency strikes in September — six months from the next window. She either waits it out, drawing on other savings in the meantime, or attempts the same thin exchange market Vikram faced, with no guarantee of a fair-price buyer.
Same starting amount, same unplanned emergency, three very different outcomes — driven entirely by fund structure, not by fund performance or asset quality.
8. How to Spot the Structure Before You Invest
You don't need to guess. Every scheme's structure is disclosed clearly if you know where to look:
Check the scheme name. Words like "Series I/II/III," "FMP," "Fixed Maturity Plan," "Interval," or "Yearly/Quarterly/Monthly Plan" are strong giveaways of a closed-ended or interval structure. A plain name like "Flexi Cap Fund" or "Corporate Bond Fund" with no such suffix is almost always open-ended.
Read the Scheme Information Document (SID). Every mutual fund's SID has an explicit section titled "Type of Scheme," stating in plain language whether it is open-ended, closed-ended, or interval, and — for the latter two — the exact maturity date or transaction window schedule.
Check for exchange listing. If a fund's units are listed on NSE or BSE and traded like a stock (searchable by a ticker symbol, showing bid/ask prices), that is a closed-ended or interval fund. Open-ended non-ETF schemes are never individually listed this way.
Tip
The fastest check of all: if the fund lets you set up a monthly SIP right now, on any app, it's open-ended. Closed-ended and interval funds simply don't offer this — new money can only enter during their specific, narrow windows.
9. Taxation: The One Thing Structure Doesn't Change
Here's a fact that surprises many investors: mutual fund taxation in India depends on what the fund invests in, not on its structure. An open-ended equity fund and a closed-ended equity fund holding similar portfolios are taxed identically. Structure is invisible to the tax code — only the underlying asset allocation matters.
Equity-Oriented Funds (65% or more in equity)
- Short-Term Capital Gains (STCG): units held under 12 months — taxed at 20%
- Long-Term Capital Gains (LTCG): units held over 12 months — 12.5% on gains above ₹1.25 lakh per year (gains up to ₹1.25 lakh remain tax-free)
This applies whether the equity fund is open-ended, closed-ended, or (theoretically) an interval scheme — the wrapper doesn't matter.
"Specified Mutual Funds" — Debt-Heavy Funds With 35% or Less Equity
This is the category that captures nearly every Indian interval fund and most closed-ended debt schemes like FMPs, for units acquired on or after 1 April 2023. Under Section 50AA, all gains are added to your income and taxed at your applicable slab rate, irrespective of how long you've held the units. There's no LTCG concept, no indexation benefit, for this category anymore. Units bought before 1 April 2023 continue to be governed by the older rules (LTCG at 20% with indexation, for holdings beyond 36 months) under grandfathering provisions.
Hybrid Funds With Equity Between 35% and 65%
These fall outside the "Specified Mutual Fund" definition (since equity exceeds 35%) but also fall short of the equity-oriented threshold (65%). They are taxed as "other than equity-oriented" funds: LTCG at 12.5% without indexation for units held beyond 24 months, and STCG at your slab rate for shorter holding periods.
| Fund Type | STCG | LTCG |
|---|---|---|
| Equity-oriented (≥65% equity) | 20% (< 12 months) | 12.5% above ₹1.25 lakh/year (> 12 months) |
| Specified/debt-oriented (≤35% equity, bought on/after 1 Apr 2023) | Slab rate, any holding period | Slab rate, any holding period (no LTCG concept) |
| Hybrid (35–65% equity) | Slab rate (< 24 months) | 12.5%, no indexation (> 24 months) |
Warning
This is a simplified summary of a genuinely intricate area of tax law, and grandfathering rules for pre-April-2023 purchases add further nuance. Please treat this as a starting point for understanding the shape of the rules, not as a substitute for advice from a Chartered Accountant on your specific holdings.
10. SEBI's Rulebook: The Guardrails Behind Each Structure
SEBI's regulations don't just define these three structures on paper — they actively shape how each one behaves in practice:
For open-ended funds: AMCs must deploy the money collected in an NFO within a set number of business days, preventing prolonged idle cash. Senior fund management staff are required to have "skin in the game" — personal investments in the schemes they manage, aligning their incentives with unit-holders'.
For closed-ended funds: The NFO subscription period is capped, mandatory exchange listing follows shortly after the NFO closes, and independent valuation norms apply to keep NAV calculations honest even when the underlying portfolio includes less liquid instruments.
For interval funds: The transaction window must stay open for a minimum of two days, with at least a 15-day gap before the next window opens. Mandatory listing applies here too, giving a technical (if thin) exit route between windows.
These rules exist because the very features that make closed-ended and interval structures useful for fund managers — locked capital, freedom from redemption pressure — are exactly the features that can trap retail investors if left unchecked. SEBI's framework is essentially a set of investor-protection guardrails wrapped around a structure that, by design, limits your control over your own money for stretches of time.
11. Real Numbers: How Rare Are Closed-Ended and Interval Funds, Really?
It's one thing to say these structures are "less common." It's another to see the actual scale. According to AMFI's industry data for March 2026, the entire Indian mutual fund industry managed assets of roughly ₹73.73 lakh crore. Of this enormous pool, closed-ended and interval schemes combined accounted for only around ₹24,763 crore — a share of roughly 0.34% of total industry assets.
The folio count tells the same story from a different angle. Of the industry's approximately 27.39 crore total investor folios in March 2026, closed-ended and interval schemes together held only around 4.82 lakh folios — about 0.18% of the total.
Put differently: for every ₹1,000 sitting in Indian mutual funds today, roughly ₹3.40 sits in a closed-ended or interval scheme. Everything else — the overwhelming, near-total remainder — is open-ended.
The monthly trend adds another layer. AMFI's flow data for this combined category has shown net outflows in several recent months, as older closed-ended schemes mature and pay out their proceeds faster than new ones are launched to replace them. This isn't a category quietly growing in the background — it's a shrinking sliver of an industry that has, for well over a decade, been consolidating almost entirely around the open-ended structure.
12. A Brief History: Why Closed-Ended NFOs Boomed, Then Nearly Vanished
Closed-ended funds weren't always this rare. Go back to 2014, and the picture looked very different: that year alone saw a record 75 equity NFOs launched in India, raising roughly ₹12,200 crore — and of those, 51 were closed-ended schemes, which together mobilised close to 80% of all the money raised through NFOs that year. Many of these were closed-ended ELSS ("tax-saving") series — schemes that offered Section 80C tax deduction along with the enforced discipline of a fixed lock-in, and they sold well precisely because investors liked the idea of a scheme that prevented them from prematurely exiting a tax-saving investment.
That boom didn't last. A cap on distributor commissions that took effect in 2016 made closed-ended NFOs considerably less attractive for distributors to push, and new launches slowed sharply the following year. Then, in 2017–18, SEBI's broader scheme-categorisation and rationalisation push nudged the industry firmly toward standardised, comparable, largely open-ended categories — leaving little regulatory or commercial incentive to keep launching new closed-ended equity series. What survives from that era today is largely a long tail of old ELSS "Series" funds slowly running out their original tenures, plus occasional Fixed Maturity Plans and thematic closed-ended NFOs that AMCs still launch on a limited scale.
Interval funds never had a comparable boom to begin with — they've always occupied a narrow niche for debt-focused AMCs wanting a middle ground between a liquid fund and a Fixed Maturity Plan, and that niche has stayed narrow for exactly the reasons this guide has laid out.
13. Which Structure Fits Which Investor?
| Investor Profile | Best-Fit Structure | Why |
|---|---|---|
| Anyone running a SIP for a long-term goal | Open-ended | SIPs require the ability to invest every month; only open-ended funds offer this |
| Someone who might need emergency access to their money | Open-ended | 1–3 day redemption at NAV, no exchange dependency |
| A first-time mutual fund investor | Open-ended | Full historical track record available; simplest mechanics to understand |
| Someone with a large lumpsum and zero liquidity need for 5+ years, actively hunting exchange-traded discounts | Closed-ended (with caution) | Discipline against panic-selling, and a genuine (if niche) discount-buying opportunity for sophisticated investors |
| Someone who wants marginally higher debt yields and can plan around scheduled windows | Interval (with caution) | Slightly better yield than a liquid fund, in exchange for scheduled rather than daily liquidity |
| Almost every other investor | Open-ended | Full stop |
Notice how lopsided this table is. That's not an editorial accident — it reflects how the actual product landscape and the actual needs of the vast majority of retail investors line up.
14. Common Myths About Fund Structure, Debunked
Myth 1: "Closed-ended funds are safer because your money is locked away from market swings." Locking your capital doesn't reduce market risk — the fund still holds the same volatile stocks or bonds, and its NAV still moves with the market every single day. What locking removes is your behavioural ability to panic-sell, which can be a genuine benefit for undisciplined investors, but it is not the same thing as reduced investment risk.
Myth 2: "If a closed-ended fund is listed on the stock exchange, I can always sell it when I need to." Technically true, practically unreliable. Thin trading volumes mean you may find no buyer at all, or only a buyer willing to pay a steep discount to NAV. Treat the listing as a possible bonus exit, never as guaranteed liquidity.
Myth 3: "Interval funds are basically liquid funds with a slightly better return." Liquid funds let you exit any business day. Interval funds gate your exit to specific windows that might be months apart. The extra yield compensates for genuinely reduced liquidity, not a cosmetic inconvenience.
Myth 4: "A new closed-ended NFO is a bargain because it's launching at ₹10 per unit." The ₹10 face value at launch is meaningless — it's simply where every new scheme's NAV starts. It tells you nothing about whether the fund is cheap or expensive, and a brand-new closed-ended NFO has zero track record for you to evaluate the manager's skill against.
Myth 5: "Since closed-ended and interval funds are rare, they must be the 'insider' or 'exclusive' opportunity smart investors use." Rarity in this case reflects reduced practicality for most investors, not exclusivity or hidden alpha. The tiny share of industry AUM sitting in these structures is a signal that the market — both fund houses and investors — has broadly voted with its feet toward open-ended funds, not evidence of an overlooked opportunity.
15. Quick Reference: Everything in One Place
The Three Structures at a Glance
| Open-Ended | Closed-Ended | Interval | |
|---|---|---|---|
| Can you SIP into it? | Yes | No | Rarely |
| Track record at purchase | Full history | None (new NFO) | Depends on series |
| Exit route | AMC, any business day | Exchange only, until maturity | Exchange between windows; AMC during windows |
| Typical tenure | None (perpetual) | 3–7 years | None (perpetual, gated) |
| Share of industry AUM | >99.5% | <0.5% combined | <0.5% combined |
| Good for | Almost everyone | Disciplined, illiquid-comfortable lumpsum investors | Debt investors who can plan around fixed windows |
Key Rules to Remember
- Open-ended = default and dominant. No maturity, daily liquidity, full SIP support.
- Closed-ended = fixed-term commitment. NFO entry only, locked until maturity, exchange listing is a thin safety valve, not real liquidity.
- Interval = gated liquidity. Scheduled windows only, mostly debt-oriented in India, taxed at slab rate under Section 50AA for units bought after April 2023.
- Taxation depends on the portfolio, not the structure. An equity fund is taxed the same way whether it's open-ended or closed-ended.
- Structure is disclosed upfront. Check the scheme name and the SID before you invest a single rupee.
Numbers to Keep in Mind
- 30 days — the maximum NFO subscription period for a closed-ended scheme under SEBI rules
- 2 days — the minimum length of an interval fund's transaction window
- 15 days — the minimum gap SEBI requires between two interval fund transaction windows
- ~₹73.73 lakh crore — total Indian mutual fund industry AUM (March 2026)
- ~₹24,763 crore — combined AUM of all closed-ended and interval schemes in India (March 2026) — about 0.34% of the industry
- ~4.82 lakh — combined investor folios in closed-ended and interval schemes, versus roughly 27.39 crore folios industry-wide
- 6–8.5% — typical historical annualised returns for debt-oriented interval funds
- 35% — the equity-allocation threshold below which a fund becomes a "Specified Mutual Fund" taxed at slab rate regardless of holding period (Section 50AA, effective April 2023)
16. Why This Website Analyses Only Open-Ended Direct Growth Funds and ETFs
If you've read our other guides, you already know this website tracks only Direct plan, Growth option funds, plus ETFs. This blog adds a third and final piece to that picture: every fund we analyse is also open-ended. Here is the complete reasoning.
Reason 1: Closed-Ended and Interval Funds Have No Meaningful Track Record to Analyse
A closed-ended NFO, by definition, has zero performance history the day it launches — you're evaluating a strategy and a manager's reputation, not a demonstrated result. Once it does build a track record, its finite tenure means that history disappears entirely at maturity, with a fresh, unrelated Series replacing it. There is no continuous, comparable performance line to chart the way there is for an open-ended fund that's been running for fifteen years. Interval funds fare only marginally better, given how few of them exist and how thinly their limited history is spread across scattered series.
Reason 2: Exchange-Traded Prices Distort Any Comparison
For a closed-ended or interval fund, the price an investor actually realises on exit often isn't the NAV — it's whatever premium or discount thin exchange trading produces on that day. Building fund analysis and comparison tools around NAV data alone would misrepresent what investors in these structures actually experience; building them around exchange prices would mean analysing something with almost no trading volume to make the data meaningful in the first place. Neither option produces the kind of clean, comparable dataset this site is built on.
Reason 3: The Numbers Speak for Themselves
As the previous sections showed, closed-ended and interval schemes together represent roughly 0.34% of the entire Indian mutual fund industry's assets and about 0.18% of all investor folios. Building detailed analysis infrastructure for a corner of the market this small — one that's shrinking rather than growing, with a persistently negative net flow trend — would mean directing our limited research effort toward funds that are structurally unavailable to the vast majority of readers at any given time (since most only accept money during brief, one-off NFO windows or specific transaction periods).
Reason 4: Our Purpose Is Actionable Analysis for the Investor Reading This Right Now
The evidence across every section of this guide points the same way: for the overwhelming majority of investors, with the overwhelming majority of financial goals, an open-ended fund is the structurally correct choice. It's the only structure that lets you start today, invest via SIP, exit when your life circumstances demand it, and compare fifteen years of clean, NAV-based performance data before you commit a rupee. Every open-ended Direct Growth fund and every ETF we analyse on this site meets that bar. Closed-ended and interval funds, by their very design, don't — not because they're bad products in an absolute sense, but because they solve for a narrow set of circumstances that describe very few of the people reading this.
17. Final Word: Structure Is the Question Behind Every Other Question
Before you ever ask whether a fund is a good large-cap fund, or whether its expense ratio is competitive, or whether its fund manager has a strong track record, there's a prior question that determines whether any of those other questions even matter to you: can you get your money out when you need it?
Open-ended funds answer that question with an unqualified yes, every single business day, for as long as you hold them. Closed-ended and interval funds answer it with a conditional maybe — maybe at maturity, maybe during a scheduled window, maybe on an exchange if a buyer happens to show up at a fair price. For the disciplined, patient, lumpsum investor who has genuinely thought through their liquidity needs, that conditional maybe can occasionally be worth the trade-off. For almost everyone else — anyone running a SIP, anyone who might face an emergency, anyone who wants to compare a fund's real history before investing — it isn't.
This website's entire analytical foundation rests on open-ended Direct Growth funds and ETFs, because that combination is where transparency, liquidity, comparability, and practical usefulness for the ordinary Indian investor all converge. When you see a fund analysed here, you're looking at something you can act on today, exit tomorrow if you truly need to, and trust the historical numbers behind, because they were never distorted by a locked tenure or a thin exchange price in the first place.
This blog is for educational purposes and reflects rules in force for FY 2025-26 (AY 2026-27), along with the Section 50AA debt-fund taxation framework effective from April 2023. Tax laws and SEBI regulations are subject to change. This is not personalised investment or tax advice. Please consult a SEBI-registered investment adviser or a Chartered Accountant for advice specific to your situation. Past performance of mutual funds is not indicative of future returns.